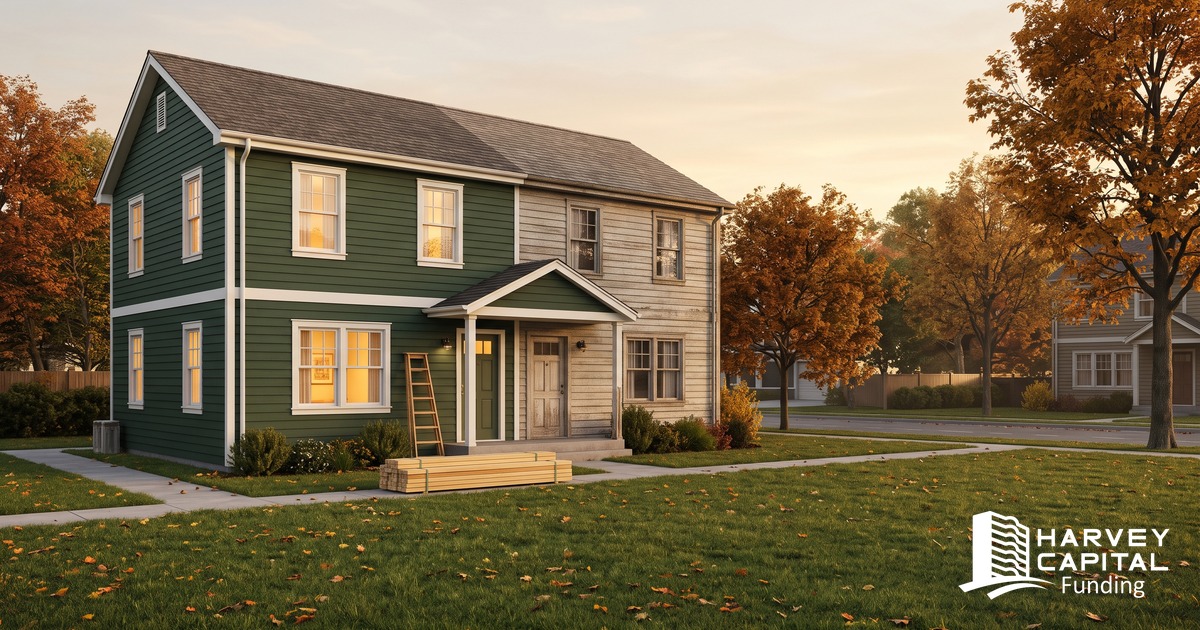
Farmville, Virginia. A 1940 duplex, 1,530 square feet: three bedrooms and a bath upstairs, a one-bedroom walk-out unit below. It sits a mile from Longwood University and, according to the listing, has been rented continuously since 1990. The operator has a full-time job, and this is his first investment property. It is also the third deal he brought us. Here is how he got here, the loan, and what happens next.
The First Two Deals
He first came to us in August with a house in Henrico County under contract at $330,000, with about $125,000 of renovation planned. Our value for the finished house came in close to his, around $540,000. The problem was the price. It was $40,000 to $67,000 above what nearby sales supported, and the all-in cost landed at roughly $538,000. That leaves no margin for anyone, so we passed and told him why in those numbers.
In September he sent a second house, in Richmond, and asked us to value it. Our number came in about 5% under his.
In October he sent this one.
The Deal
The duplex listed on Friday, October 2, at $114,900. On Tuesday, October 6, he emailed us asking for a pre-approval letter he could submit with an offer, and he had a term sheet and a $120,000 pre-approval letter that day. He offered $120,000, over the list price, and the contract was ratified on Wednesday, October 7.
The plan is to renovate both units and hold the building as a rental. The units brought in $1,550 a month when he bought it: $1,000 for the lower unit and $550 upstairs at a discounted rate. His $70,000 renovation covers both kitchens, both baths, flooring, lighting and the mechanicals, with asbestos testing and the heating-oil tank written into the scope. What an old oil tank can cost a buyer is in The Oil Tank in the Yard.
A small rental near a college is valued on its rents. We built our number from what renovated units near campus are asking now, about $2,650 a month for the two units, and valued the building the way a buyer of a small rental would. That gives $225,000. He projects higher rents after the renovation, and he may be right, but we lend against our number. Sales of comparable small multifamily buildings nearby were too thin to lean on, which is why the rents set the value.
The Loan
$157,500, in two pieces:
- $87,500 at closing, 73% of the $120,000 purchase price.
- $70,000 renovation holdback, released in draws as the work is verified. The holdback covers 100% of his renovation budget.
The loan is 70% of our $225,000 value on the finished building and 83% of his $190,000 total cost. Six-month term, interest only, paid monthly. 3 points and a $995 flat fee. He brought $32,500 to the purchase, 27% of the price.
Why 73% of the purchase and not 90%? It is his first project, so there are no exits yet for us to verify on the county record, and the value came from rents in a market with few comparable sales. A first project with thin comps starts lower on the purchase advance. Verified exits are what move it up on the next one. We explain how that number gets set in How We Size the Purchase Advance.
The Timeline
- August. First deal. We passed, with the numbers.
- September. Second house valued.
- Friday, October 2. The duplex listed at $114,900.
- Tuesday, October 6. He asked for a pre-approval letter and had it the same day, with a term sheet.
- Wednesday, October 7. Contract ratified at $120,000.
- Friday, October 23. Funded, three weeks after the listing went up.
For what that letter says and how to use it with an offer, see What Our Pre-Approval Letter Tells a Seller, and How to Use It.
What Happens Next
The renovation money comes out only against verified work. The first draw starts with a walkthrough video of both units, the electrical panel, the heating equipment and the oil tank. After that, he submits a short video of the completed work in our portal, we review it, and the draw is funded within 24 hours, $100 per draw. Our article on how we fund draws walks through it.
When both units are renovated and leased, the exit is a long-term rental loan that pays ours off. When it does, the payoff goes on our public list.
Every loan we fund is on that list, with the amount, the city, the property type, the term, and whether it is active or paid off. Never a name or a street. See the full book at /funded-deals.
If you are buying your first rental and want a pre-approval letter on a specific house before you write the offer, send the listing, your renovation budget line by line, and the rents you expect through the Discuss My Deal form, or call 804-208-0465.