
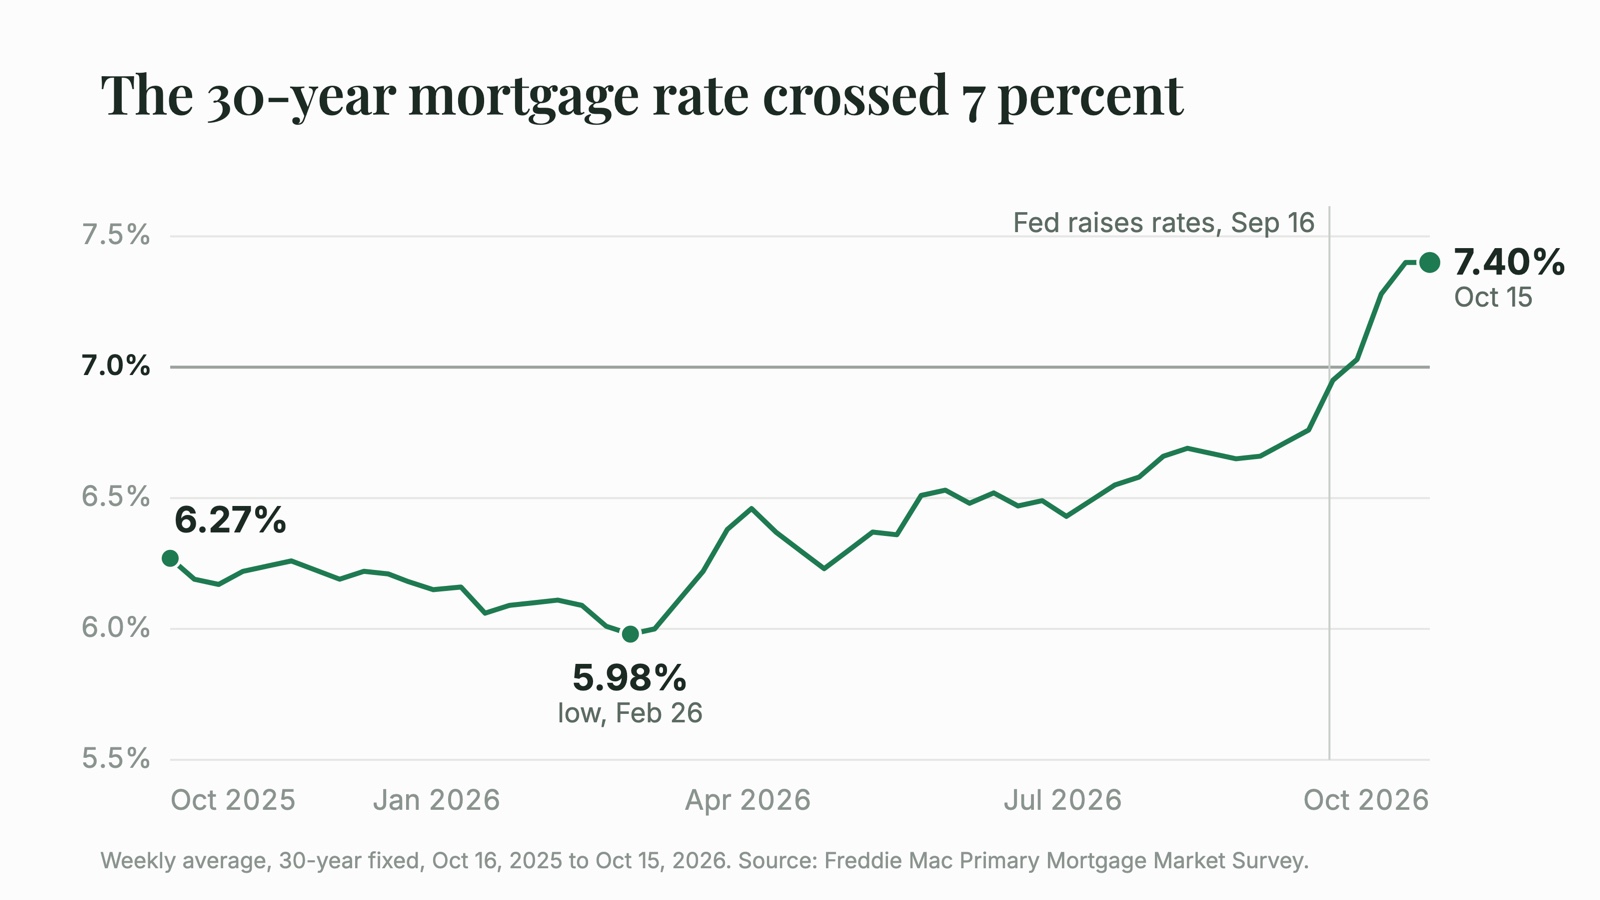
On October 15, the average 30-year fixed mortgage rate was 7.40 percent, according to Freddie Mac's weekly survey. A year earlier it was 6.27 percent. In September, the month rates crossed 7 percent, buyers in the Richmond area put 802 single-family homes under contract, 13.9 percent fewer than in September 2025.
If you sell your flips to retail buyers, their monthly payment sets your price. Here is what moved in September, what has not moved yet, and what it means for your exit and your hold.
What moved in September
The Federal Reserve raised its benchmark rate by a quarter point on September 16, to a range of 3.75 to 4 percent. It was the Fed's first increase since July 2023.
Mortgage rates were already climbing. Freddie Mac's weekly average was 6.71 percent on September 3, 7.03 percent on September 24, 7.28 percent on October 1, and 7.40 percent on both October 8 and October 15. The low of the past year was 5.98 percent, in late February.
Contracts fell. Pending sales, the count of homes that went under contract, were 802 in September against 932 a year earlier in Chesterfield, Hanover, Henrico, and Richmond city, according to CVR MLS, the Richmond-area multiple listing service. Rates are not the only cause: July was down 13.0 percent while rates were lower than the July before, and August was up 2.4 percent. For the year through September, contracts are still up 0.9 percent, because March through May ran 4 to 8 percent ahead of last year.
The MLS also tracks affordability. An index of 100 means the median household earns exactly the income needed to qualify for the median-priced home at current rates. For single-family homes it was 94 in September, down from 105 a year earlier. The median household now earns about 6 percent less than it needs to buy the median house.
What has not moved yet
The closed-sale numbers have not turned. Single-family homes that sold in September took 26 days on average to get an accepted offer, faster than 30 days a year earlier, and sold for 99.5 percent of their original list price. The median sale price was $450,000, up 4.7 percent. There were 1,851 homes for sale at the end of the month, up 5.1 percent, which works out to 2.1 months of supply against 2.0 a year ago.
Those numbers describe deals agreed to a month or two earlier, mostly before rates crossed 7 percent. Contract counts move first. Closed sales and prices follow, if they move at all.
What it does to your buyer
Take a buyer financing $300,000 on a 30-year fixed loan. At 6.27 percent, principal and interest is $1,851 a month. At 7.40 percent it is $2,077, which is $226 more.
Turn it around. The $1,851 payment that carried a $300,000 mortgage a year ago carries about $267,000 today. The same budget buys 11 percent less loan.
That does not mean prices drop 11 percent. So far they have not dropped at all, and buyers adjust in other ways: they put more down, ask for seller credits, or wait. But if your ARV leans on comps that went under contract this spring, when rates ran from about 6.0 to 6.5 percent, check them against what is going under contract now, and make sure the deal still works if your buyer can borrow less than the spring buyer could.
What it does to your hold
Fewer contracts can mean a longer wait for one, and on a private loan the wait is what costs money. In our September issue we measured the 21 loans our borrowers paid off in 2026: the median ran 172 days from funding to payoff. At 12 percent, every extra month on a $150,000 loan is $1,500 of interest. A six-month loan that runs past maturity also owes an extension fee, two points in our case, or $3,000 on $150,000.
The season adds to it. Single-family homes that sold last December through February took 33 to 36 days to get an offer, about twice the 17 to 19 days for homes that sold in May through July. If your house lists this winter, plan the hold around winter's pace and today's rates, not this summer's.
Henrico permits: September
Henrico issued 290 residential building permits in September, the most since April. Of those, 53 were renovation permits over $25,000, and residential renovation work totaled $7.8 million in declared value, the highest of the six months we have tracked (April through September ranged from $5.3 million to $7.8 million). New-home permits came in at 110.
Operators were still starting projects in September. A renovation permit comes after the purchase and the scope of work, so these mostly reflect decisions made over the summer, before rates crossed 7 percent.
Source: Henrico County Open Data, monthly building permit reports, April through September 2026. Richmond city, Chesterfield, and Hanover still do not publish a comparable monthly file.
Sources for this piece: Freddie Mac Primary Mortgage Market Survey, weekly 30-year fixed average; Federal Reserve FOMC statement, September 16, 2026; CVR MLS Monthly Indicators, Richmond Metro (Chesterfield, Hanover, Henrico, Richmond city), September 2026, single-family homes, data current as of October 10, 2026; Henrico County Open Data. Payment figures are principal and interest only.
This piece is Issue #6 of the Central VA Real Estate Insider, our monthly Substack for operators. Past issues are collected at harveycapitalfunding.com/insights.