
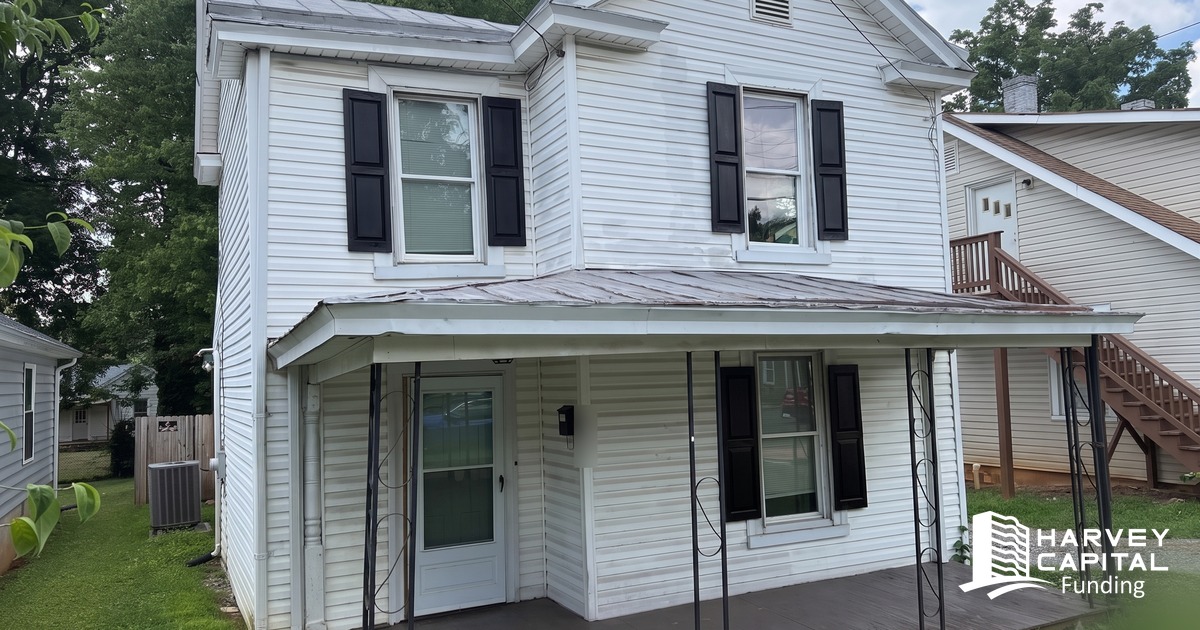
Lynchburg, Virginia. A two-story single-family house built in 1905: three bedrooms, one bath, about 1,525 square feet on the county record. The operator bought it in June for $80,000, renovated it, placed a tenant, and refinanced it into a long-term rental loan. The refinance lender's appraisal came in at $170,000, and our loan was paid off 47 days after it funded.
What the Operator Bought
As it stood, the house was worth roughly $100,000. The operator bought it for about $20,000 under that number.
The plan was a BRRRR: buy the house, renovate it, rent it, and refinance into a long-term rental loan. The refinance would pay off our loan, and the house would stay with the operator as a rental. The operator paid for the renovation with their own money, so there was no holdback on our loan and no draw schedule to run.
The operator is a repeat borrower with a long record with us.
How We Sized the Loan
The operator's application listed an after-repair value of $140,000. Our own comparable sales put the house at $170,000. We sized the loan to the lower number.
- $90,000 first lien, six-month term, interest only
- 64% of the operator's $140,000 after-repair value
- Rate-only pricing: zero points and a $700 document fee
- No renovation holdback
- No prepayment penalty
On the operator's own number, that left $50,000 of value above our loan. At 64% of the operator's value, the loan did not depend on our higher number being right.
The Refinance
The dates on the file:
- June 19: our loan funded
- July 31: the operator signed the refinance into a long-term rental loan
- August 5: our loan was paid off, 47 days after it funded
In the six weeks between our funding and the refinance, the operator renovated the house and placed a tenant. That work was the operator's from start to finish: the plan, the renovation money, the tenant, and the refinance. Buy, renovate, rent, and refinance all happened inside the first two months of a six-month term.
The refinance lender's appraisal came in at $170,000, the same number our comps produced. Our $90,000 was 53% of it. The $30,000 between the $140,000 the loan was sized to and the $170,000 appraisal belongs to the operator.
What the Loan Cost
Rate-only pricing means no points. What the operator paid us was interest for the days our loan was out, plus the document fee. The operator used 47 days of a six-month term. With no prepayment penalty, that meant 47 days of interest and the $700 fee, and nothing for the months they did not use.
Our article on how a payoff works shows what is on a payoff statement and how the daily interest figure works.
What This Means for Your Deal
Three things worth taking from this file.
First, the operator bought about $20,000 under the house's as-is value. That $20,000 was there on the day of the purchase, before any renovation and before any appraisal, and it did not depend on anyone's after-repair value.
Second, ask your refinance lender for its seasoning rule before you buy. This refinance was signed 42 days after our loan funded, and not every refinance lender will lend on a new appraisal this soon. Our article on refinance seasoning covers the rules, including when a refinance lender will use the new appraisal.
Third, if you plan to pay for the renovation yourself, as this operator did, budget that money apart from your closing. Our article on cash to close covers what you need at the purchase closing.
This loan is on our funded-deals list. If you have a house under contract, or an address you are deciding on, call 804-208-0465 or use the Discuss My Deal form. We will pull our own comps and tell you where we land on value and why.