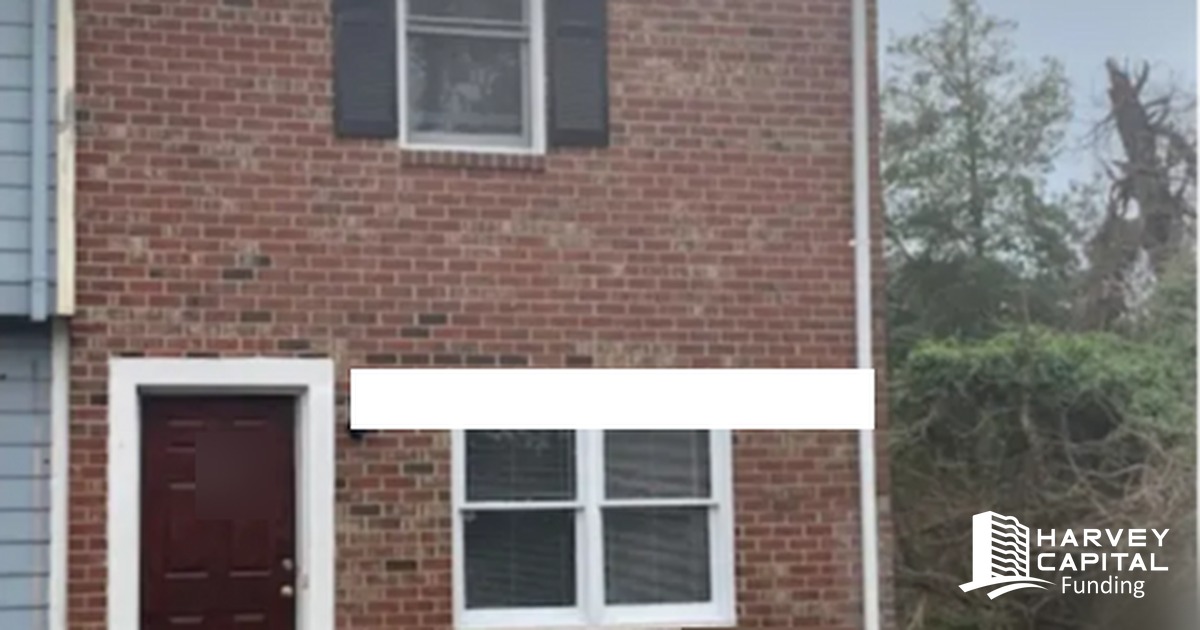
A Virginia investor owned a two-bedroom townhome in Greenville, North Carolina, free and clear. A stabilized rental with a Section 8 tenant paying $1,096 a month, no mortgage, no liens. On paper, the easiest collateral in the world. In practice, almost nobody would touch it.
The Asset Nobody Would Lend On
Not because the deal was weak — because the loan was small. He wanted to pull capital out of the property without selling it, and the loan that made sense was $45,000. Banks quote 45 to 60 days of underwriting on a request like that, and many won't bother at all: a $45,000 loan takes nearly as much work as a $450,000 one, and the economics don't excite them. Most hard money lenders have minimums that start above it.
So the equity just sat there. A performing rental, full of capital, doing exactly one job when it could do two.
What We Did
He first reached out on July 1. On July 17, we wired a $45,000 first lien against the townhome.
The numbers:
- Property value: $90,000
- Loan: $45,000 — a 50% loan-to-value first lien
- Term: 6 months
- Tenant: in place the whole time, rent uninterrupted
Sixteen days from first contact to wire — and that included a full title review, insurance placement, and the closing work of any first-lien loan. He kept the house. He kept the tenant. He kept the $1,096 a month. And the equity that had been sitting in the walls became working capital.
Why We Said Yes When Others Wouldn't
The short answer: the collateral and the borrower both checked out, and we underwrite the deal in front of us instead of running it through a minimum-loan-size filter.
At 50% loan-to-value with a paying tenant covering the carry, this was a strong loan — the size didn't change that. We'd rather write a clean $45,000 first lien than a shaky $300,000 one, and our process doesn't get cheaper to run at $300,000, so we don't price small loans out of existence.
The Takeaway for Operators Holding Paid-Off Rentals
A free-and-clear rental feels great. It's also idle capital. If you're holding one — or several — that equity can fund your next acquisition without forcing you to sell a performing asset, give up a tenant, or wait two months on a bank.
If you've got a paid-off property and a use for the capital, call us at 804-208-0465. If it's a fit, you'll know quickly.