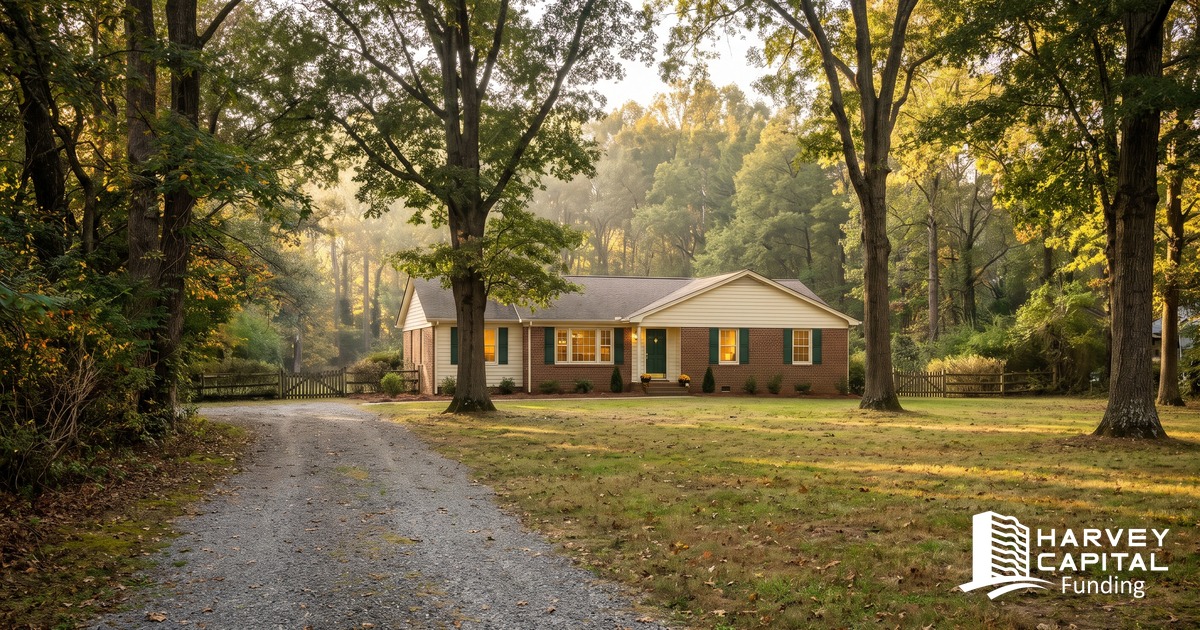
Westmoreland County, Virginia. A 1983 single-story ranch: three bedrooms, two baths, 1,260 square feet on 1.76 acres. It listed at $94,500, and two days later the operator had it under contract at $85,000. She found us on Google on a Thursday afternoon. We funded the following Thursday. Here is the deal, the loan, and what the week looked like.
The Deal
The house needed a full renovation. Her budget: $80,000. Her exit: sell it when the work is done.
Renovated resales in that part of the county have been landing between $219,000 and $258,000. We set the after-repair value at $250,000. Purchase plus renovation comes to $165,000, which is 66% of that number before a dollar of interest or fees. That margin is what made the loan easy to size.
This was our first loan in Westmoreland County. The underwrite was the one we run in Richmond or Lynchburg: the same comp pull on the same radius, the same 70% cap, the same questions about the exit. The price points on the Northern Neck are different. The math is not.
The Loan
$152,250, in two pieces:
- $72,250 at closing, which is 85% of the $85,000 purchase price.
- $80,000 renovation holdback, released in draws as the work gets done. The holdback covers 100% of her renovation budget.
The loan is 61% of the $250,000 after-repair value, under our 70% cap. Six-month term, maturing April 15, 2027, with two 90-day extensions available at 2 points each if she needs them. 3 points and a $995 flat fee, both deducted from our wire at closing. No prepayment penalty.
Her cash at the table: $12,750 for the 15% of the purchase we did not advance, $4,567.50 in points, the $995 fee, interest to the end of October, and the title company's own items. Every renovation dollar is on our side.
Why 85% and not 90% or 95%? This was her first loan with us, with no exits yet for us to verify on the county record, and a strong deal on the margin side. We explain how the purchase advance gets set in How We Size the Purchase Advance.
The Week
- Thursday, October 8. First call.
- Friday and Saturday. Most of her file was uploaded within 48 hours: entity documents, bank statements, her experience sheet, and the contract, which already named her title company.
- Saturday, October 10. Terms went out, with a six-month option and a nine-month option.
- Sunday, October 11. She accepted and chose six months.
- Monday, October 12. Title and insurance were ordered. The last of her file came in.
- Thursday, October 15. Funded.
Seven days from the first call to the wire. The underwriting took about as long as it always does. The file is what moved.
What Happens Next
The $80,000 holdback funds in draws. She submits a short video walkthrough of the completed work in our portal, we review it, and the draw is funded within 24 hours, $100 per draw. Our article on how we fund draws walks through it. When the house sells, the loan pays off and the payoff goes on our public list. If the sale runs past April, the two 90-day extensions are already priced on her term sheet, so a slower market is a known cost rather than a surprise.
Every loan we fund is on that list, with the amount, the city, the property type, the term, and whether it is active or paid off. Never a name or a street. See the full book at /funded-deals.
If you have a house under contract in Virginia and a renovation budget with numbers next to each line, send it through the Discuss My Deal form or call 804-208-0465. If your file is ready on day one, a week is a realistic closing date.