
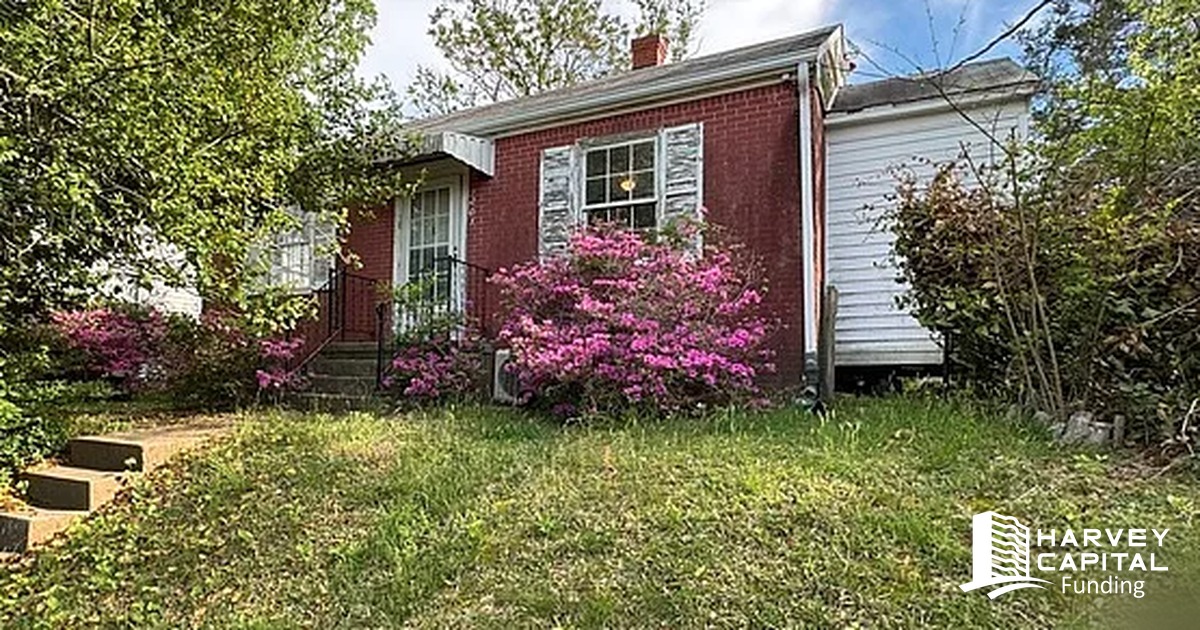
A new borrower came to us late last year with a single-family house in Richmond. He had it under contract for $130,000, a plan to renovate it and keep it as a rental, and a need for a lender who could fund the purchase and the renovation without making him empty his bank account to do it. He had never borrowed from us before. He walked away with the whole deal funded — and roughly $4,500 out of his own pocket.
New to us didn't mean starting from zero
A lot of lenders treat a first-time borrower like a risk to be priced up — a higher rate, a bigger down payment, more hoops. We don't think being new to us is the same thing as being unproven.
When we looked at this borrower, we didn't see someone we'd never worked with. We saw an operator who already owned 22 rental properties, all financed on long-term loans. That told us what we needed to know: he knows how to buy, he knows how to renovate, and — most importantly for a short-term loan like ours — he knows how to refinance into permanent debt and pay his lender back. The exit our loan depends on was something he had already done 22 times.
So we got to yes quickly, and we did it on the same terms we'd offer a borrower we'd known for years.
We funded the purchase and the renovation in one loan
The house was a $130,000 purchase with about $17,000 of renovation work planned. We structured a single loan that covered both: the purchase and the rehab budget.
At closing, we wired the money to buy the house. The borrower brought about $4,500 to the table — a fraction of what most lenders require. There was no separate construction loan to arrange, no second closing, no scramble to find rehab capital after the purchase. One loan, one closing, the whole project covered.
That's the point of working with a lender who controls its own capital. We don't answer to a warehouse line or a credit committee that caps how much of a deal we can fund. When the numbers make sense — and on this house, the borrower was buying a property worth around $200,000 once fixed up for $130,000 — we can fund the whole thing and move.
The renovation money was there when he wanted it
We held the $17,000 of renovation funds and made them available to draw as the work got done. The borrower controlled the timeline. He drew what he needed, when he needed it, against work completed — no waiting on us to approve a budget line before he could keep his crew moving.
As it turned out, he moved so fast on the back end that he refinanced and paid us off before he ever needed to pull the renovation money down. That's his call to make, not ours. The money was ready; he simply didn't need it from us by the time he was done.
He paid us off early — and there was no penalty for it
The loan was written for nine months. He paid it off in less than six, refinancing into a long-term DSCR loan — rental financing that let him keep the house as a cash-flowing rental.
We didn't charge him a thing for paying us back early. No prepayment penalty, no minimum-interest clause, no "you owe us the rest of the term anyway." When a borrower is ready to refinance us out, we want them to. A loan that pays off early is a loan that worked — for him and for us.
Why we could do all of this
Speed, full-stack funding, low money down, no prepayment penalty, and a fast yes for a borrower new to us — those aren't favors. They're the natural result of how we're built.
We lend our own capital. We make our own credit decisions. We're focused on the Central Virginia market, so a house in Richmond is in our backyard, not a dot on a national map. And we'd rather build a relationship with an operator who's going to bring us his next ten deals than squeeze the most we can out of his first one.
This borrower was new to us in December. He won't be new to us next time.
Got a deal?
If you're buying, renovating, and refinancing in Central Virginia and you want a lender who can fund the purchase and the rehab, move quickly, and treat your first deal like it's not your last — let's talk. Tell us about your deal on Discuss My Deal. It takes about a minute, and we'll respond the same day.