Rocky Mount, Virginia. An operator bought a house and six apartments in one purchase, sold the house first, refinanced the apartments, and paid off a $580,000 loan in 188 days.
The Property
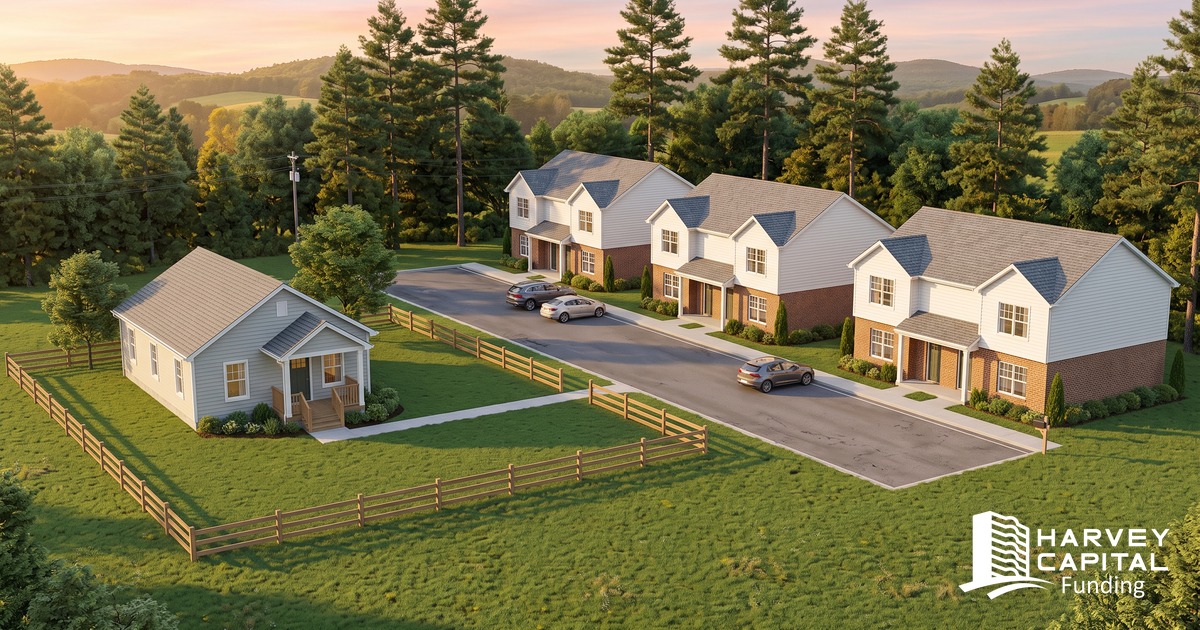
Two adjoining tax parcels, bought from one seller in March 2026 as two transactions that closed the same day. The first is about half an acre with a single-story house on it: two bedrooms, one bath, a full basement, built in 1996. The second is about 1.7 acres with three two-story duplex buildings, six apartments in all, each two bedrooms and one bath.
The operator had borrowed from us before, and the plan was straightforward. Stabilize the apartments, refinance them into long-term debt, and sell the house.
The Structure
One note and one first deed of trust covering both parcels. $580,000, six months, interest only, funded in full at closing on March 6. No renovation holdback and no draws. The apartments and the house secured the same loan together.
That is the normal way to finance a purchase like this, and it raises a question worth asking before you close: what happens if one piece is ready to sell before the rest is ready to refinance? A deed of trust does not release part of the collateral on its own. Somebody has to decide what it costs.
The Release
In August the house found a buyer at about $150,000, ready to close before the apartment refinance was. The operator called and asked us to release the house from the loan so the sale did not have to wait.
We set the release at a flat $119,000, which was what the house had cost him in March. All of it went to principal. No release fee and no per diem on top; the regular monthly interest simply kept running on the balance. Releasing a parcel for what it cost going in means the property left behind carries the rest of the loan on the same footing it did the day we funded, so the answer could be yes on the first call.
The sale closed in early September on his buyer's schedule. We recorded a partial release for the house parcel only, the deed of trust stayed in place on the apartments for the remaining $461,000, and he kept the rest of the sale proceeds.
The Exit
On September 10 the apartment refinance closed and paid the loan off in full. 188 days from funding to payoff, four days past the six-month maturity.
We did not charge an extension fee. A refinance that lands a few days late for reasons that have nothing to do with the borrower is not what an extension exists for.
What This Means for Your Deal
If you are buying more than one property in one purchase, or putting more than one property behind one loan, ask your lender before closing what it takes to release one of them early. What does it cost, how is the number set, and who decides. On this loan the answer was the house's purchase price, and it took one phone call. On other multi-property loans we can write the release price into the note at closing, so you know the number before you ever need it.
The operator did his part. He had a buyer, a clean sale, and an apartment refinance already moving. Our part was making sure the loan did not stand between him and the sale.
If you have a multi-property purchase coming, call 804-208-0465 or use the Discuss My Deal form. We will tell you how we would structure it, including what a release would cost, before you sign anything.